Tell us your situation. We will model the exact bridging cost.
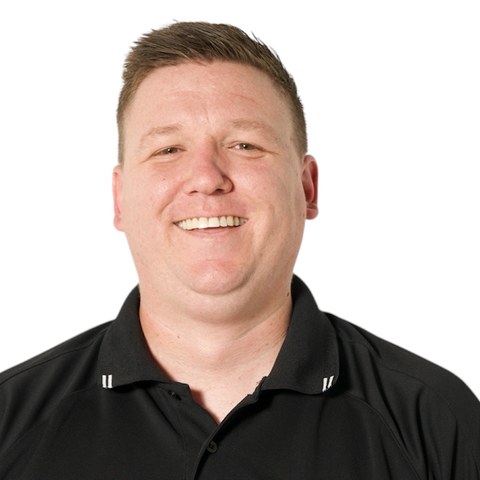
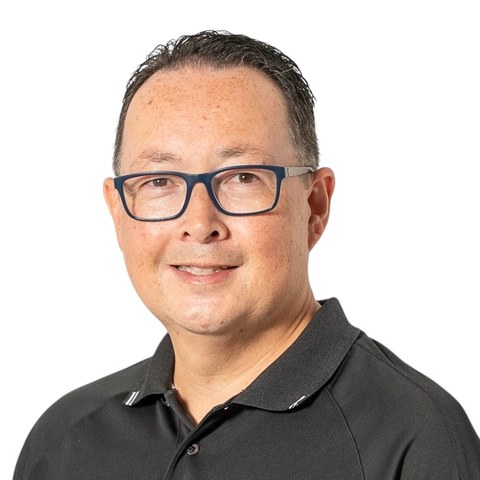
A short, honest assessment from Jason or Steve. We calculate your peak debt, monthly interest cost and end position and reply within one business day. No fee from us - the lender pays us when your loan settles.

Jason does the legwork. Your part is one 15-minute call.
Jason calculates your peak debt, models the interest cost at different sale timelines, compares lenders who will bridge new customers and confirms your end position before you commit.
Jason founded Lendology to give Adelaide borrowers honest, expert advice. His particular strength is complex and non-standard lending. Broking since 2018, he holds the MFPA designation, one of the first four awarded in South Australia.
Most lenders only bridge their own customers. Your options are wider than you think.
The numbers are ours. The decision is yours.
- Model the full cost - peak debt, monthly interest and end position, before you commit to anything.
- Compare lenders who will bridge new customers, such as BankSA, Westpac, Bridgit and MA Money, alongside your current bank.
- Stress-test your sale timeline, so you know the worst case if the sale takes longer than expected.
- Arrange pre-approval on your new property, so you can move quickly when you find the right home.
- Manage both settlements, coordinating with your real estate agent, conveyancer and lender.
When bridging may not be the right choice
- Your sale timeline or price is uncertain. Selling first may be a safer approach.
- Your home is not yet under contract. An open bridge is assessed more conservatively because the sale timeline is uncertain.
- The sale runs past the agreed period. You may need to renegotiate or refinance.
- You sell for less than expected. The end debt on your new home will be higher than planned.
Lendology models both options honestly, bridging and selling first, and lets you decide.
From first call to settlement
Full cost modelling
We calculate the exact bridging interest cost from your property values, mortgage balance, purchase price and estimated sale timeline.
Lender selection
Not all lenders offer bridging. We find the most competitive option, including lenders who will bridge new-to-bank clients.
Pre-approval
We arrange pre-approval on your new property while the bridging structure is prepared, so you can move quickly.
Settlement coordination
We manage both settlements, coordinating with your real estate agent, conveyancer and lender throughout.
What we check before recommending anything
- Peak debt, and your LVR at peak
- Whether interest can be capitalised
- Open or closed bridge
- Your sale timeline, at the full period
- End debt, serviceable on your income
- What happens if you sell for less
What clients say
The questions people ask us
"Bridging costs too much."
The cost is a known, fixed amount based on peak debt and bridging period. Lendology calculates it to the dollar before you commit. In many cases the bridging interest is less than the cost of selling first, renting, storing furniture and moving twice.
"What if my house does not sell?"
Lenders allow 6 to 12 months. In the current Adelaide market, well-priced properties are selling within 4 to 8 weeks. Lendology stress-tests the cost at the full bridging period so you know the worst case before you start.
"I will just sell first, then buy."
Selling first means you compete for your next home without certainty, risk losing it to a faster buyer, and may need to rent in between. Bridging lets you buy with confidence and sell without pressure.
How much does a bridging loan cost?
Bridging loan interest is charged on the peak debt - the combined balance of your existing mortgage and new purchase price. The cost depends on both balances, the interest rate and the length of the bridging period. Lendology calculates the exact cost for your situation before you commit to anything.
How long can I have a bridging loan?
Most lenders allow bridging periods of 6 to 12 months. If your current property is not sold within the agreed period, you may need to renegotiate or refinance. Lendology assesses realistic sale timelines and stress-tests the cost if the sale takes longer than expected.
Can I use a bridging loan if I already have a mortgage?
Yes - bridging finance temporarily combines your existing mortgage with the new purchase loan during the transition period. The existing mortgage is repaid when your current property settles, leaving you with just the end loan on the new property.
Is bridging always the right choice?
Not always. If the bridging period is likely to be short and the market is favourable, bridging can be cost-effective. If there is uncertainty about your sale timeline or price, selling first may be a safer approach. Lendology models both options honestly and lets you decide.
Can I bridge if my current lender does not offer it?
Yes. Most lenders only bridge existing customers, but BankSA and Westpac will bridge new-to-bank clients. Bridgit and MA Money are specialist bridging lenders. Lendology compares all available options.
What is the difference between an open and closed bridge?
A closed bridge means you have already exchanged contracts on your existing home, so the sale end date is confirmed. An open bridge means your home is listed but not yet under contract. Closed bridges are lower risk and often have better terms.
Do I make repayments during the bridging period?
Most lenders allow interest to be capitalised during the bridging period. That means interest is added to the loan balance rather than paid monthly. You do not make repayments on two loans at the same time.
What happens if I sell for less than expected?
If your property sells for less than expected, the end debt on your new home will be higher than planned. Lendology models this scenario upfront so you understand the range of outcomes before committing.
Do your own homework
Find out what bridging will actually cost.
We calculate your peak debt, model the interest cost at different sale timelines and confirm your end position, with no obligation to proceed.
No fee from us. The lender pays us when your loan settles.