Banks assess self-employed income conservatively. The right lender makes all the difference.
Self-employed borrowers are not higher risk - they are different risk. Banks with rigid serviceability models often decline or under-assess self-employed income. Lenders who understand business income, trust distributions, director fees and irregular cash flow assess your position more accurately. Lendology identifies those lenders before lodging a single application.
15 minutes with Jason or Steve. No cost to you, the lender pays us when your loan settles. You pick a time, we call you.
The Lendology process
Google rating
Read all reviews →Go deeper
FAQs
How many years do I need to be self-employed to get a home loan?
What income documents do I need?
What is a low-doc home loan?
Can I borrow if my business has had a difficult year?
You might also be interested in
Adelaide suburbs we serve
Self-employed home loan help across Adelaide - specialist advice for business owners and contractors.
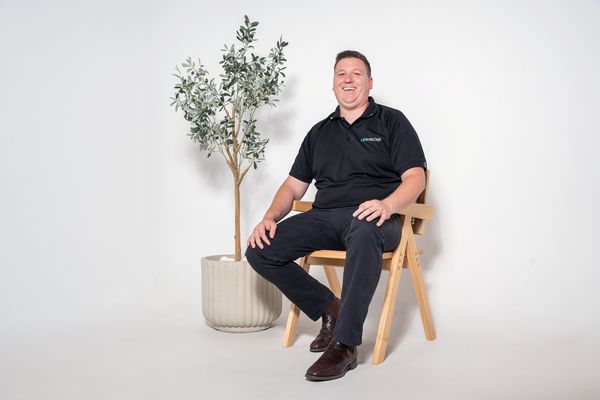
Jason Given MFPA
Director & Mortgage Broker
Jason founded Lendology to give Adelaide borrowers honest, expert advice that is genuinely in their corner. His particular strength is in complex and non-standard lending - self-employed borrowers, company directors, trust structures, multiple entities, and anyone whose income does not fit neatly into a payslip. He holds the MFPA designation - one of the first four awarded in South Australia.
Send us a message instead.
We respond to all enquiries within one business day - usually the same day.